
The income velocity of money is the average number of times one unit of currency is used to buy newly produced goods and services during a year. The formula is simple: divide nominal GDP (total national income) by the money supply. If an economy produces 20 trillion in nominal output and holds 10 trillion in money, its income velocity is 2.
That single number tells economists a lot. It shows whether money is circulating quickly or sitting idle, and it helps explain why printing more money does not always push prices up right away. In this guide, you will learn the meaning, the formula, a worked example, the factors that move velocity, and how to read the data like an analyst.
What Is the Income Velocity of Money?
Income velocity of money measures how fast money moves through an economy in exchange for final goods and services. It counts only payments that become someone's income, such as wages, profits, rent and interest. Purchases of existing assets, like second-hand property or shares, are left out.
Think of a single coin. You pay a baker, the baker pays a flour supplier, and the supplier pays a driver. The same coin has now created income three times. Across millions of people, the average number of these hand-offs in one year is the income velocity.
A higher number means each unit of money works harder. A lower number means people and businesses are holding more of their cash instead of spending it.
What Is the Formula for Income Velocity of Money?
The standard formula is:
V = Y ÷ M
Here, V is income velocity, Y is nominal national income (usually nominal GDP), and M is the average money supply over the same period. The formula comes from the quantity theory of money, written as M × V = P × Y, where P is the price level and Y is real output. Since P × Y equals nominal GDP, the shortcut above works.
How Do You Calculate Income Velocity Step by Step?
First, pick a period, usually one year. Second, find nominal GDP for that period. Third, choose a money measure, such as narrow money (cash and checking deposits) or broad money (which adds savings-type deposits). Finally, divide GDP by the average money stock.
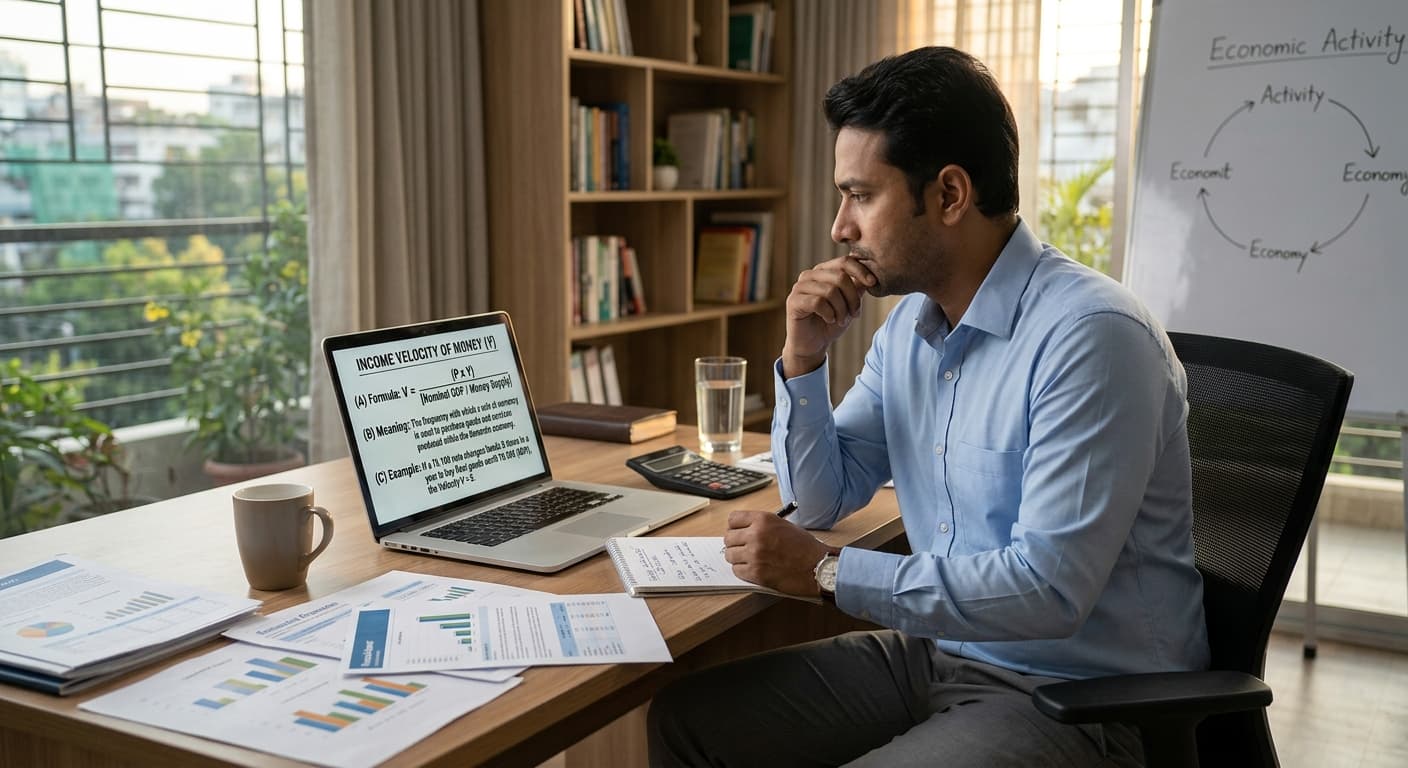
The explanation of this topic is given in the image above:

Here is a simple example you can follow with a calculator.
A velocity of 1.5 means each unit of broad money supported about 1.5 units of income during the year. If GDP rises to 27 trillion while money stays at 16 trillion, velocity climbs to about 1.69, which suggests money is changing hands faster.
Always state which money measure you used. Velocity based on narrow money will be far higher than velocity based on broad money, and mixing them is the most common error beginners make when comparing charts.
What Is the Difference Between Income Velocity and Transactions Velocity?
Income velocity looks only at money used to pay for final goods and services that make up national income. Transactions velocity counts every payment in the economy, including financial trades, business-to-business payments and resales of existing assets.
Why Does the Income Velocity of Money Matter?
Velocity matters because it links the money supply to prices and growth. If velocity stays stable, then a faster rise in money than in real output should push prices up. That is the classic monetarist argument.
But velocity is not always stable. When it falls sharply, extra money can enter the economy without causing much inflation, because people simply save it. When it rises quickly, even a modest money supply can fuel strong price pressure. Central banks watch velocity for exactly this reason: it shows how much of their money creation actually reaches spending.
Investors and business owners also use it as a mood gauge. Rising velocity often signals confidence, while falling velocity often signals caution or fear.
What Factors Affect the Income Velocity of Money?
Several forces push velocity up or down, and they usually work together rather than alone.
How Do Interest Rates Change Velocity?
When interest rates are high, holding idle cash is costly, so people move money into savings and investments or spend it sooner. Velocity tends to rise. When rates are near zero, holding cash costs almost nothing, and velocity tends to fall.
How Do Confidence and Expectations Matter?
In uncertain times, households build emergency savings and firms delay investment. Money sits in accounts longer. In optimistic periods, spending comes faster. Expectations about inflation also play a role: if people expect prices to rise, they spend sooner, which lifts velocity.
Does Technology Affect Velocity?
Yes. Digital wallets, card payments and instant transfers make it easier to spend and to move money between accounts. Faster settlement can raise the pace of circulation, although it can also make it easier for people to park funds in savings, so the net effect varies.
What Role Does Financial Development Play?
In economies with deep banking and credit systems, people hold more money in savings-type accounts that count in broad money. This can lower measured velocity over the long run even when spending is healthy. That is why a low number is not automatically a bad sign.
What Does High or Low Income Velocity Tell Us?
A high velocity suggests active spending, strong confidence and a tighter link between money and prices. A low velocity suggests saving, caution or a large pool of money that is not being spent.
Remember that velocity is an average. It cannot tell you who is spending and who is saving, so it should be read alongside other indicators.
How Has Income Velocity Changed Over Time?
Long-run data from a very large advanced economy shows how dramatic the swings can be. Using a broad money measure, velocity climbed to roughly 2.2 in the late 1990s, then drifted lower through the 2000s and 2010s. It fell sharply to about 1.1 in the second quarter of 2020, when output dropped and households saved heavily, and then recovered partly to around 1.3–1.4 in the following years. These figures are approximate and are rounded for clarity.
PeriodApproximate Broad-Money VelocityLate 1990sAbout 2.2Mid-2000sAbout 1.9–2.02019About 1.4Mid-2020 (lowest point)About 1.1Recent yearsAbout 1.3–1.4The lesson is clear. Velocity can change a lot even within a few quarters, so assuming it is constant is risky. For exact and current values, check the official data portals listed at the end of this guide.
How Can You Read Velocity Data Like an Analyst?
Start with the trend, not a single reading. A one-quarter spike or dip can come from a temporary shock, while a multi-year slope reflects structural change.
Practical tip: When I compare velocity charts, I first check three things: the money measure used, whether GDP is nominal or real, and whether the series is seasonally adjusted. Skipping any of these can turn a clean comparison into a misleading one.
Another useful habit: Pair velocity with the growth rate of money and with an inflation measure. If money is growing fast, velocity is falling, and prices are stable, the extra money is probably being saved. If all three rise together, inflation risk deserves attention.
What Are the Limitations of Income Velocity?
Income velocity is a derived number, not something you can observe directly. It depends on how money is defined, and definitions vary between institutions. It also hides differences between households, since a small group may hold a large share of idle money. Finally, the formula treats velocity as a result, so it does not explain the causes by itself. Use it as a clue, not a verdict.
Authoritative Sources to Verify and Explore Further
For current data and deeper reading, consult these reputable sources: the International Monetary Fund (imf.org), the World Bank Open Data portal (data.worldbank.org), the Bank for International Settlements (bis.org), the OECD Data portal (data.oecd.org), and the FRED database of the Federal Reserve Bank of St. Louis (fred.stlouisfed.org), which publishes ready-made velocity charts. Always confirm the latest figures there before publishing.
Final Thoughts
The income velocity of money turns a big idea into a simple ratio: nominal income divided by the money supply. It shows how actively money is being used, links money to prices, and acts as a quick gauge of confidence in the economy. The key points to remember are the formula V = Y ÷ M, the importance of choosing a consistent money measure, and the fact that velocity moves with interest rates, expectations, technology and financial depth. Track the trend, compare it with money growth and inflation, and you will understand far more than the headline number alone suggests.
Frequently Asked Questions
What is the income velocity of money in simple words?
It is the average number of times a unit of money is spent on final goods and services in a year. A higher value means money circulates faster.
What is the income velocity of money formula?
The formula is V = Y ÷ M, where Y is nominal GDP and M is the average money supply for the same period.
Is a high velocity of money good or bad?
Neither by itself. High velocity often reflects confidence and strong spending, but combined with rapid money growth it can raise inflation risk. Low velocity can signal caution or heavy saving.
What is the difference between income velocity and transactions velocity?
Income velocity counts only payments for final output, while transactions velocity counts all payments, including financial and resale transactions.
Why does velocity fall during a downturn?
Households and firms save more and spend less, so money changes hands more slowly while output also drops.
Which money measure should I use to calculate velocity?
Choose one and stay consistent. Narrow money gives a higher velocity, broad money gives a lower one, and comparisons only make sense within the same measure.